The 7 Percent Question: How Central Oregon Buyers and Sellers Can Work With Today’s Rates
By Ask Porter | September 13, 2026
BEND, Ore. - If you’ve been to an open house in Bend lately, you already know the first question people ask. It isn’t about the kitchen or the school district. It’s about the rate. And as of Friday, the answer starts with a seven.
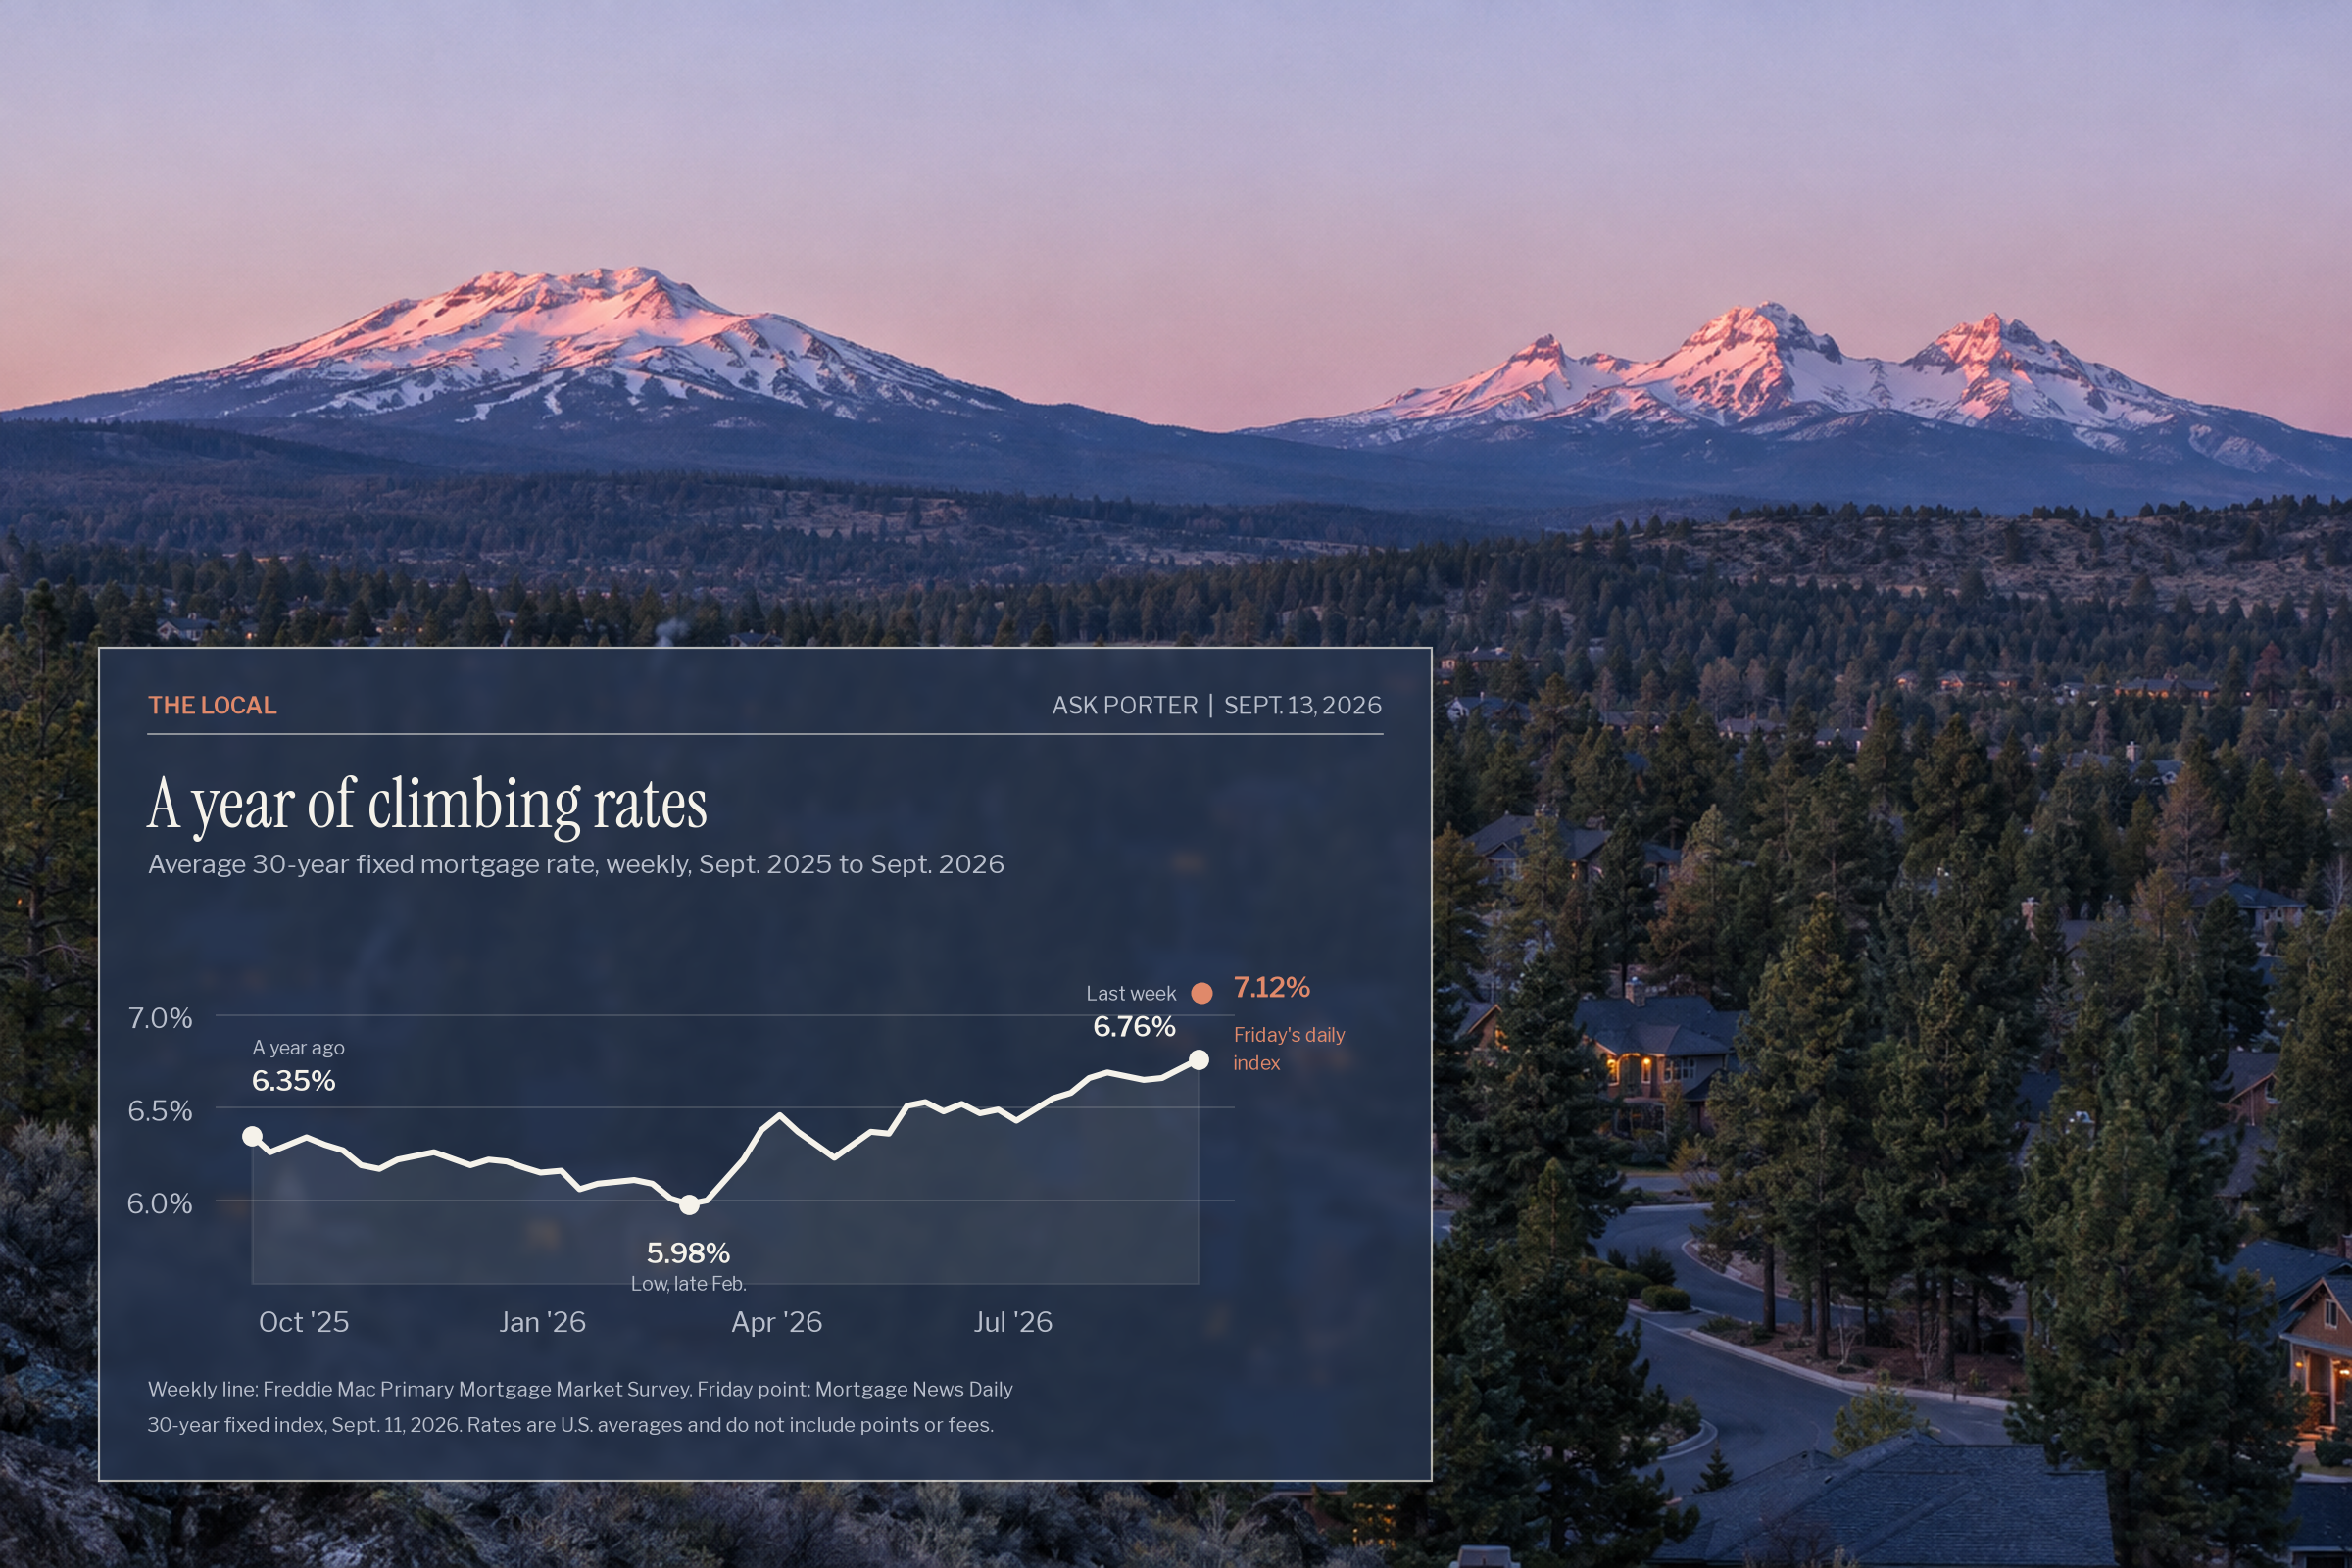
Mortgage News Daily’s index, which tracks actual lender rate sheets each day, put the average 30-year fixed at 7.12 percent at Friday’s close, the highest level since early 2025. Freddie Mac’s weekly survey, the number most people see in headlines, came in at 6.76 percent on Thursday, but that survey closes Wednesday and missed the late-week jump. A year ago, Freddie Mac had the 30-year at 6.35 percent.
Nobody I talk to expected rates to be higher this September than last. But that’s where we are. Friday’s inflation report showed consumer prices up 0.4 percent in August and 3.4 percent over the past year, and gasoline alone accounted for more than a third of the monthly jump. The Federal Reserve meets Tuesday and Wednesday with its benchmark rate at 3.50 to 3.75 percent, where it has been all year. After Friday’s numbers, futures markets are pricing in close to a 90 percent chance of a quarter-point increase. That would be the first hike since July 2023. As recently as Wednesday, a Reuters poll of economists had leaned toward the Fed holding steady. The 10-year Treasury yield, which mortgage rates tend to follow, is sitting just under 5 percent.
So the rate relief a lot of people were waiting on isn’t just delayed. It’s going the other way.
What 7 percent costs in Bend
Let’s put real numbers on it. The median single-family home in Bend sold for $721,000 in August, according to the Beacon Appraisal Group’s monthly report, which pulls from the MLS of Central Oregon. Put 20 percent down and you’re borrowing about $577,000. At 7.12 percent, principal and interest run about $3,884 a month. At last September’s 6.35 percent, that same loan was about $3,589. The difference is $295 a month, or roughly $3,500 a year.
That’s real money, and it’s why the phones got quieter this week. But a lot of buyers are still measuring today’s payment against the 3 percent mortgage their neighbor got in 2021, and that comparison, more than the actual rate, is what’s keeping qualified people on the sidelines.
The market is moving anyway
Here’s the part the national headlines miss: Bend didn’t freeze. This summer was the busiest stretch we’ve seen in years, with 201 single-family closings in June and 187 in July, the two strongest months on the Beacon Report’s three-year chart. August added 160 more. Inventory has held steady at 3.5 months, with roughly 520 single-family homes on the market. Over in Redmond, where the August median was $480,000, inventory sits at about four months.
Prices, meanwhile, have basically stayed put. Zillow’s home value index for Bend is down 0.8 percent over the past year, and Redfin’s three-month median sale price of $699,000 is off 1.6 percent. After the run-up of the early 2020s, we’ve had three years of prices bouncing around inside the same range.
Flat prices, steady inventory, and rates over 7 percent make for a market where strategy matters more than speed. That’s true whether you’re buying or selling.
For buyers: negotiate the rate, not just the price
Shop the loan. Sam Khater, Freddie Mac’s chief economist, said this week that getting multiple quotes “can potentially save them thousands.” He’s right, and almost nobody does it. On Sunday, national lender quotes on the same 30-year loan ranged from the high sixes to the mid sevens.
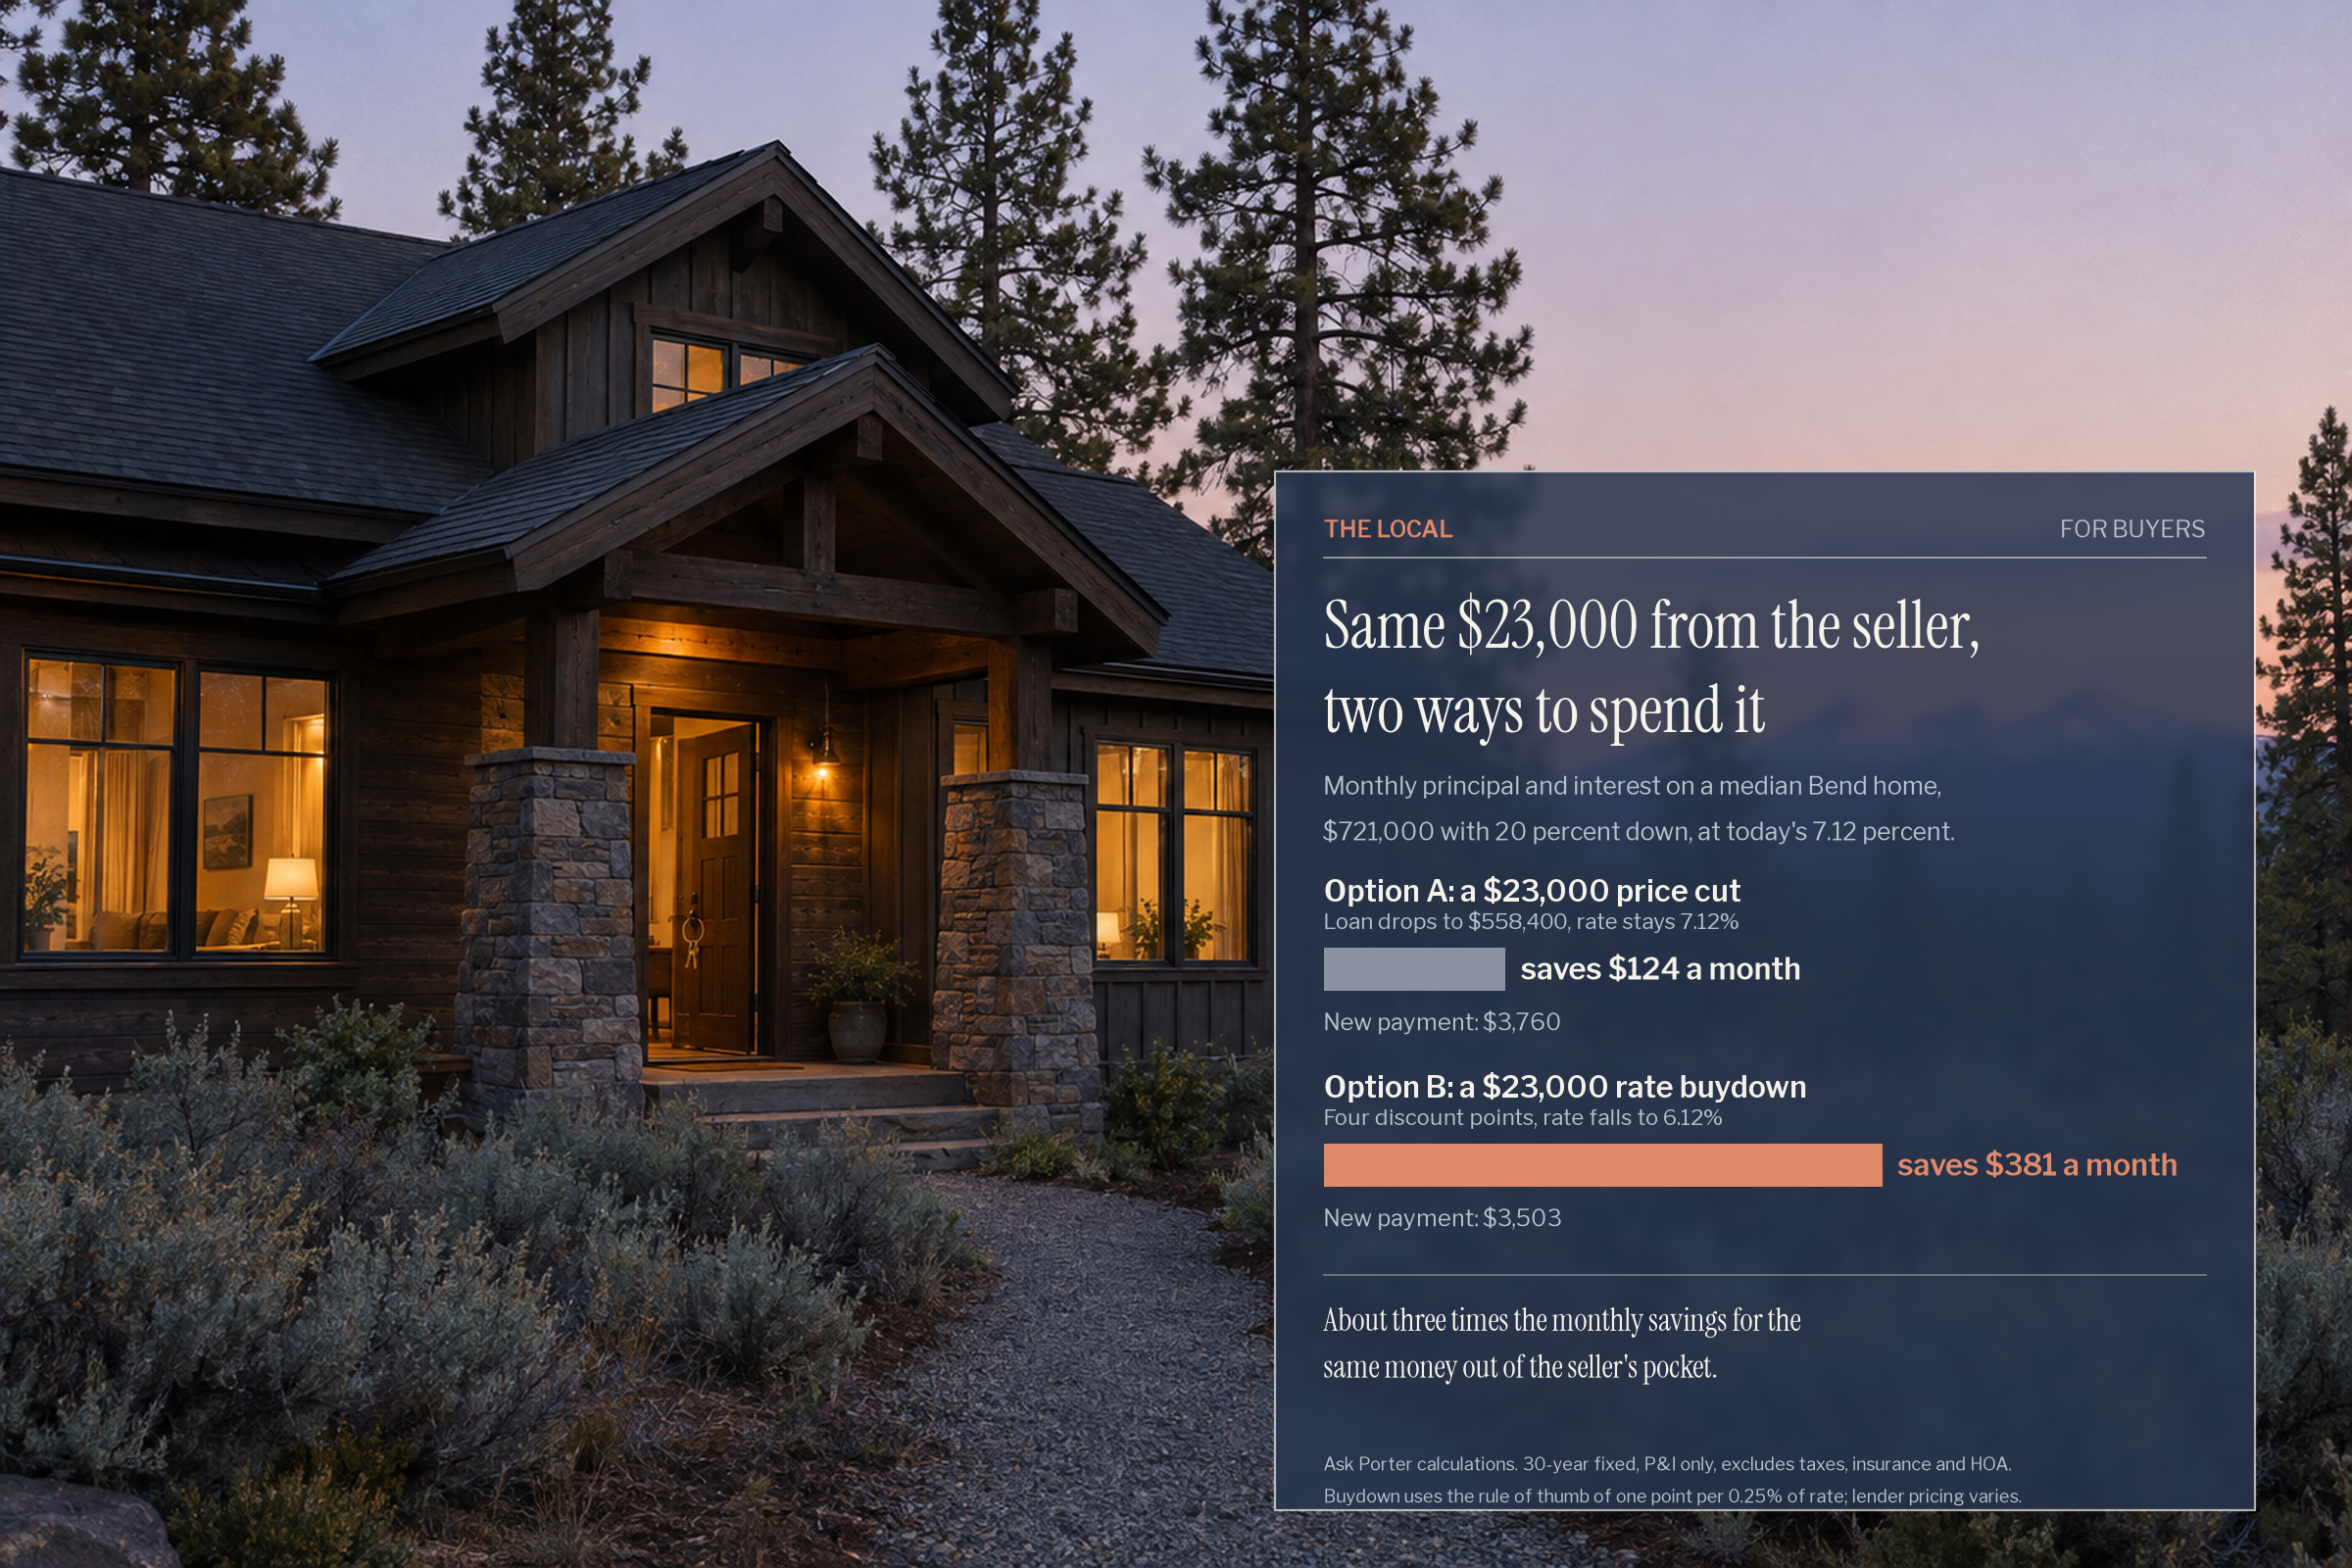
Ask for a rate buydown instead of a price cut. A discount point costs 1 percent of the loan and usually knocks about a quarter point off the rate. So buying that $577,000 loan down a full point, to 6.12 percent, would cost roughly $23,000 and bring the payment down to about $3,503. If the seller instead cut the price by $23,000, you’d save about $120 a month. Same money out of the seller’s pocket, and the buydown saves you about three times as much every month.
Go after the listings that have been sitting. Nearly 60 percent of Bend homes that sell go pending in their first 30 days, and they sell for about 99.3 percent of asking. The ones that make it to a second month close about 5 percent below the original list price, and homes that linger into months three, four and five see average discounts closer to 11 percent. Not everything is negotiable right now. The trick is knowing which homes are.
Buy for the payment, not the forecast. If a house fits your life at today’s payment, a refinance down the road is a bonus. If it only works at a rate that hasn’t shown up yet, keep waiting.
For sellers: price it right the first time
The same numbers should give sellers pause. Roughly a third of Bend listings get canceled, withdrawn, or expire without selling. The homes that get full price are the ones priced correctly from day one. The ones that start high and chase the market down almost always end up giving back more than a sharp opening price would have cost.
Budget for concessions. With rates over 7 percent, offering to pay for a buyer’s rate buydown or cover closing costs is often the cheapest way to widen your pool of buyers without touching your list price.
Don’t be afraid of fall. Fewer new listings come on between now and January, and the buyers who are out looking in October tend to be serious. A well-priced home with less competition can do better than one that waits for the spring rush and all the other sellers who wait for it too.
The bottom line
None of us in Bend can control what the Fed does Wednesday. But the people who closed on homes this summer figured something out that the folks waiting on the sidelines haven’t: the rate is just one number in the deal. Work the payment, use the leverage the market is handing you, and let 7 percent be someone else’s problem.
A note on timing: this was written Sunday, Sept. 13, ahead of the Fed’s Sept. 15-16 meeting. The 7.12 percent figure is Mortgage News Daily’s index as of Friday, Sept. 11. Freddie Mac’s weekly average, released Sept. 10, was 6.76 percent.
Sources
Mortgage News Daily, Daily Rate Index, Sept. 11, 2026: https://www.mortgagenewsdaily.com/mortgage-rates
Freddie Mac, Primary Mortgage Market Survey, Sept. 10, 2026: https://freddiemac.gcs-web.com/news-releases/news-release-details/mortgage-rates-average-676[gcs-web]
U.S. Bureau of Labor Statistics, Consumer Price Index, August 2026: https://www.bls.gov/news.release/cpi.nr0.htm[bls]
Reuters, “US consumer prices accelerate in August, push Fed closer to rate hike,” Sept. 11, 2026: https://www.reuters.com/world/us/us-consumer-inflation-picks-up-august-2026-09-11/[reuters]
CNBC, “CPI inflation report August 2026,” Sept. 11, 2026: https://www.cnbc.com/2026/09/11/cpi-inflation-report-august-2026.html[cnbc]
Reuters, “Fed to hold rates steady in rest of 2026; rising number of analysts see at least one hike,” Sept. 9, 2026: https://www.reuters.com/business/fed-hold-rates-steady-rest-2026-rising-number-analysts-see-least-one-hike-2026-09-09/[reuters]
NerdWallet, Mortgage Rates, as of Sept. 13, 2026: https://www.nerdwallet.com/mortgages/mortgage-rates
Zillow Home Loans, Today’s Mortgage Rates, as of Sept. 13, 2026: https://www.zillow.com/homeloans/mortgage-rates/
Zillow, “What Are Mortgage Points and Should You Buy Them?”: https://www.zillow.com/learn/mortgage-points/[zillow]
Beacon Appraisal Group / MLS of Central Oregon, Central Oregon Market Insights, September 2026 edition: https://isellbendoregon.com/market-insights-september-2026/[isellbendoregon]
Bend Relocation Services, August 2026 Housing Market Report for Central Oregon: https://bendrelo.com/august-2026-housing-market-report-for-central-oregon/[bendrelo]
Zillow, Bend, OR Home Values, data through Aug. 31, 2026: https://www.zillow.com/home-values/50962/bend-or/[zillow]
Redfin, Bend Housing Market Trends: https://www.redfin.com/city/1543/OR/Bend/housing-market[redfin]
Payment examples are Ask Porter calculations assuming a 30-year fixed loan of $576,800 (20 percent down on $721,000), principal and interest only, not including taxes, insurance, or HOA. Buydown cost uses the rule of thumb of one discount point per 0.25 percent of rate reduction; actual pricing varies by lender and market conditions.